


Chapter 5 - Section 5.5SHG Graduation to Enterprises
The SHG movement in India has evolved from a savings-and-credit mechanism into an important platform for women-led livelihoods, micro-enterprise development and local economic participation. The next stage of inclusion lies in enabling mature SHG members to undertake viable enterprises and participate more effectively in markets.


SHG-Bank Linkage Programme: Moving from Financial Inclusion to overall wellbeing
5.5 SHG Graduation to Enterprises
The SHG movement in India has evolved from a savings-and-credit mechanism into an important platform for women-led livelihoods, micro-enterprise development and local economic participation. While regular savings, internal lending and bank linkage remain the foundation of the SHG-Bank Linkage Programme, the next stage of inclusion lies in enabling mature SHG members to undertake viable enterprises, improve household incomes and participate more effectively in markets.
5.5.1 Graduation Pathways: From SHG to Enterprise
The enterprise journey of SHG members is generally gradual and non-linear. Members may enter, exit or move between stages depending on business performance, seasonal income patterns, household responsibilities, market conditions and access to finance. A typical progression begins with collective savings and small internal loans, followed by group-based bank credit for livelihood activities, and subsequently moves towards individual or collective enterprise financing.
Table 5.2: SHG Graduation Pathway
| Sl. No. | Stage | Focus | Institutional Support |
|---|---|---|---|
| 1 | Financial Inclusion | Savings, internal lending, building credit history | NRLM, Banks, NABARD, CSOs, Sa-Dhan |
| 2 | Livelihood Diversification | Identification of livelihood opportunities, skill mapping and skill development. | NRLM, Banks, NABARD, CSOs |
| 3 | Micro-Enterprise Initiation | Setting up small individual/group enterprises through Credit/Grant support | NRLM, Banks, NABARD, MUDRA, Govt. Departments |
| 4 | Enterprise Scaling | Market linkages, formalisation, MSME integration | NRLM, MUDRA (Tarun/Tarun Plus), Banks, MoMSME, NABARD, Sa-Dhan |
5.5.2 Institutional Approaches on Enterprise Graduation for SHGs/Members
Enterprise graduation among SHG members requires coordinated support from government programmes, banks, development finance institutions, training agencies, market platforms and community institutions. The institutional ecosystem plays an important role in helping women move from basic financial inclusion to enterprise ownership, growth and market participation.
5.5.2.1 Government of India and DAY-NRLM initiatives
The Ministry of Rural Development, through the Deendayal Antyodaya Yojana–National Rural Livelihoods Mission (DAY-NRLM), has positioned enterprise promotion as an important component of the SHG ecosystem. DAY-NRLM supports SHG members and their households through livelihood planning, skills development, credit linkage, enterprise incubation, community institutions and convergence with other government programmes.
The Start-up Village Entrepreneurship Programme (SVEP) is a key initiative under DAY-NRLM for promoting rural non-farm enterprises. The programme supports SHG members and their family members in setting up and strengthening micro-enterprises through finance, incubation and skill development. A key feature of the programme is the Community Resource Person-Enterprise Promotion cadre, which provides local-level support for business planning, credit linkage, training, market access and early-stage handholding. Around 3.74 lakh non-farm enterprises had been promoted under SVEP as of 30 June 2025.
The Lakhpati Didi initiative provides a clear income-oriented framework for SHG graduation. The initiative seeks to enable SHG women to achieve sustainable annual household incomes of at least ₹1 lakh through diversified livelihoods, enterprise activities, skill development, access to finance and market linkages. As of August 2026, 3.44 crore women had been identified or reported as Lakhpati Didis, with Maharashtra, Bihar and West Bengal among the leading states. The Government has set a revised target of creating 6 crore Lakhpati Didis by March 2029.
The Pradhan Mantri MUDRA Yojana (PMMY) provides an important credit bridge for SHG members graduating from group-based loans to individual micro-enterprise finance. Through Shishu, Kishor, Tarun and Tarun Plus categories, the scheme offers collateral-free loans for non-farm micro and small enterprises. The Kishor and Tarun categories are particularly relevant for mature SHG members seeking to expand enterprises beyond the scale of regular group loans. During FY 2025-26, 15.36 lakh MUDRA loans were sanctioned to NRLM/NULM beneficiaries, amounting to ₹33,667.52 crore, of which ₹30,884.81 crore was disbursed.
Enterprise finance is also being strengthened through the DAY-NRLM’s engagement with banks. The Memorandum of Understanding with Public Sector Banks and IDBI Bank has encouraged the development of dedicated enterprise-credit products for mature SHG women. Such products aim to facilitate individual enterprise loans with larger ticket sizes and more suitable repayment structures. The FY 2026-27 DAY-NRLM credit plan proposes a distinct focus on individual SHG-member financing, with a target of 13.52 lakh individual enterprise loans aggregating ₹13,516 crore and a proposed minimum loan size of ₹1.50 lakh per loan.
The Jan Samarth Portal can also support enterprise graduation by providing a common digital platform through which SHG members and rural entrepreneurs can identify eligible credit-linked schemes, assess eligibility and access institutional finance. The portal may facilitate linkages with MUDRA, PMEGP, agriculture infrastructure and other enterprise-support schemes.
The Government’s proposed SHE-MARTs, announced in the Union Budget 2026-27, may provide an additional market-access channel for SHG enterprises. Envisaged as community-owned retail outlets operated by Cluster Level Federations, SHE-MARTs can provide SHG entrepreneurs with physical market space, product visibility, branding support and stronger consumer linkages.
5.5.2.2 NABARD initiatives
NABARD plays a significant role in strengthening enterprise capabilities among SHG members through capacity building, livelihood development, market support and institutional linkages. Its interventions are particularly important in helping SHG members progress from subsistence activities to more viable micro-enterprises.
The Micro Enterprise Development Programme (MEDP) supports SHG members through skill upgradation, entrepreneurship development and business-management training. It seeks to strengthen the ability of mature SHG members to establish or improve micro-enterprises by building technical skills, improving product quality and supporting business planning. During 2025-26, 5310 SHG members were trained through 172 MEDPs with grant assistance of ₹1.61 crore for equipping them with livelihood skills. Cumulatively, 6.28 lakh SHG members have been trained through 21,225 MEDPs with total grant support of ₹64.78 crore as on 31 March 2026.
The Livelihood and Enterprise Development Programme (LEDP) adopts a value-chain and cluster-based approach to enterprise promotion. It supports groups of SHG members in contiguous villages to undertake farm and non-farm livelihood activities, develop producer groups and improve access to production, processing, value addition and markets. This approach is particularly relevant for activities that require aggregation, common facilities, collective procurement and market coordination. During 2025-26, 9,672 SHG members were provided skill and entrepreneurship training through 112 LEDPs with an expenditure of ₹8.06 crore. As on 31 March 2026, 3.26 lakh SHG members have been supported through 2,593 LEDPs with grant support of ₹139.13 crore. The main activities included Handicrafts, Paintings, Tailoring, Fashion Designing and Embroidery, Food Processing and Value Addition, and Goat Farming/Goat Rearing.
The m-Suwidha programme - Microenterprises through Skill Upgradation for Women - is a flexible, Detailed Project Report-based intervention for SHG members seeking to establish enterprises at a larger scale. The programme supports end-to-end enterprise development through assessment of skill gaps, identification of suitable occupations, training through knowledge partners, enterprise strengthening, market tie-ups and facilitation of credit support from banks and financial institutions. As on date, ₹2.68 crore grant has been sanctioned for five projects in four states (two in Tamil Nadu, one each in Telangana, Assam and Andhra Pradesh) to strengthen the livelihood of 2300 SHG members of 09 districts.
NABARD’s market-linkage initiatives also support SHG entrepreneurs by facilitating access to digital and physical markets. Through onboarding support for ONDC and other e-commerce platforms, SHG producers can improve product visibility, access customers beyond local markets and develop digital commerce capabilities. During FY 2025-26, NABARD-supported SHG sellers generated 1,583 orders through the MyStore page on ONDC, with a turnover of approximately ₹8.03 lakh.
The proposed NABUnnati Kendras are intended to function as local enterprise-support hubs by providing handholding for enterprise identification, business planning, statutory registration, credit facilitation, branding, digital onboarding and market linkage. The initiative has been launched as a pilot in six states, with the first centre sanctioned in East Khasi Hills district of Meghalaya.
NABARD’s RuTAGe Smart Village Centres may also contribute to enterprise graduation by improving access to field-tested technologies, technical advisory, demonstrations and local enterprise opportunities. The centres are intended to connect rural households, SHGs, producer organisations, Panchayats and local institutions with technology providers, research organisations and start-ups across agriculture, renewable energy, water, sanitation, healthcare, education and other relevant sectors.
5.5.2.3 Sa-Dhan’s initiative for women enterprise promotion in SHGs
Sa-Dhan has entered into an MOU with National Rural Livelihood Mission (NRLM) for working as a Technical Support agency for promotion of women enterprises among SHGs. This project is supported by Gates Foundation. Accordingly, Sa-Dhan has taken up 4 states, viz. Assam, Chhattisgarh, Jharkhand and West Bengal, where dedicated teams are placed to support the local SRLMs in training the Vitta Sakhis and mentors/ SRLM officials. The teams also liaise with the banks in the states/ districts and help in credit linkage of the identified beneficiaries. The programme has made significant progress across its key objectives:
- Enterprise Finance & Portfolio Quality: Since inception, 1,85,305 SHG members across the intervention states have been financed, with ₹2,04,374.69 lakh in cumulative finance. Portfolio quality remains strong, with NPAs below 0.5% in Assam and West Bengal, below 1% in Jharkhand, and below 2% in Chhattisgarh.
- Capacity Building: 12,604 participants have been trained through new and refresher programmes, including 9,092 Vitta Sakhis (7,228 new and 1,864 refresher) and 3,512 SRLM officials and other cadres, including SRPs/NRPs (3,178 new and 334 refresher).
- Bank Integration: 12 Public Sector Banks have developed Business Rule Engines (BREs) to support digital appraisal and processing, while IELA has been integrated with six PSBs - Canara Bank, Indian Bank, Indian Overseas Bank, Bank of India, Union Bank of India and Punjab National Bank. Work is underway to expand integration to RRBs through the Jan Setu framework.
- Evidence & Learning: A multi-state comparative study has been initiated across Andhra Pradesh, Tamil Nadu, Maharashtra, Rajasthan, Madhya Pradesh and Tripura to examine the institutional, financial, community and socio-economic factors influencing women’s access to, uptake and utilisation of individual enterprise finance, and identify practices that can strengthen enterprise finance outcomes.
Individual Enterprise Loan Application (IELA)
Sa-Dhan efforts to support the SRLMs have also resulted in developing a digital platform for the submission of the loan application to bank branches for their monitoring and tracking. Also, it provides a seamless way to get the loan application sanctioned in a shorter time. The application is built on the existing LokOS and JanSamarth portal and integrating them for smoother data flow and validations required by banks. The IELA was launched nationwide by the Hon’ble Union Minister for Agriculture and Rural Development Shri. Shivraj Singh Chouhan on 21 February 2026 and has been rolled out to the entire country for its adoption, following pilot testing and field validation. In the intervention states, 29,729 applications have been initiated, of which 16,477 have been submitted to banks and 2,649 sanctioned. The IELA architecture, workflow and system framework is provided as under:
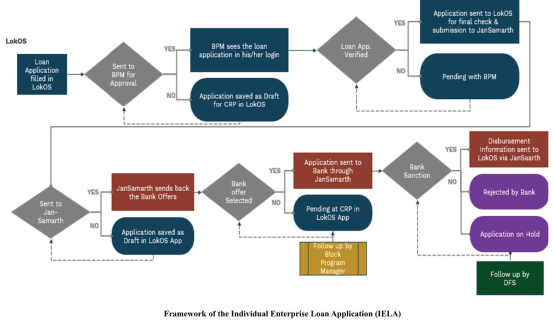
Framework of the Individual Enterprise Loan Application (IELA)
Conclusion
Together, these institutional initiatives demonstrate that enterprise graduation requires a combination of group-based financial inclusion, individual enterprise finance, skill development, incubation, market access, formalisation and technology support. The effectiveness of these interventions will depend on their ability to translate programme outreach into viable enterprises, sustained income growth, improved market participation and resilient livelihoods for SHG members.
Box 5.2: Sa-Dhan’s Partnership with DAY-NRLM Enabling Formal Finance for Women-Led Enterprises
Sa-Dhan, with support from the Gates Foundation, is providing Technical Assistance to the National Rural Livelihoods Mission (DAY-NRLM) and select SRLMs to strengthen systems for individual enterprise financing for women emerging from the Self-Help Group (SHG) ecosystem. The Gates Foundation approved the project in November 2023, followed by a formal MoU between Sa-Dhan and NRLM in March 2024. Under the partnership, Sa-Dhan functions as the Technical Support Agency (TSA) for strengthening individual women enterprise financing systems.
The programme aims to facilitate access to finance for one million women entrepreneurs across four states over five years, while strengthening the institutional and community-level ecosystem required to support sustainable women-led enterprises. Sa-Dhan’s direct intervention is being undertaken across 19 districts in four states, namely Assam, Chhattisgarh, Jharkhand and West Bengal. These districts cover approximately 5.09 lakh SHGs, providing a focused platform for strengthening enterprise-financing systems within the SHG ecosystem.
Key Objectives
The programme is structured around the following key objectives:
- Expand Enterprise Finance: Contribute to DAY-NRLM’s goal of enabling 1 million SHG women entrepreneurs to access finance, supporting the Lakhpati Didi vision through sustainable, income-generating enterprises.
- Strengthen Credit Linkages & Processes: Work with SRLMs, PSU banks and RRBs to strengthen credit linkages, streamline loan processing and address operational bottlenecks.
- Build Institutional Capacity: Strengthen the capacity of SRLM officials, Vitta Sakhis and frontline cadres to facilitate enterprise financing and engage effectively with banks.
- Enable Digital & Quality Credit: Promote technology-enabled solutions such as Individual Enterprise Loan Application (IELA) to improve application, tracking and processing, while supporting sound credit appraisal and responsible lending.
- Generate Evidence & Learning: Document field experience, identify good practices and generate evidence to inform policy, programme improvement and scale-up of women-led enterprise financing.
Institutional Innovations & Sa-Dhan’s Technical Support
As the TSA, Sa-Dhan supports DAY-NRLM and select SRLMs in strengthening the ecosystem for scaled access to formal enterprise finance for women entrepreneurs. Its support spans policy and process development, institutional capacity building, bank engagement, digital solutions and knowledge generation. Key initiatives include:
- Vitta Sakhi and Mentor Policy Frameworks: Supporting the development of structured frameworks to strengthen the cadre ecosystem and provide technical handholding.
- CLF-based Enterprise Financing Model: Supporting a community-led model to facilitate small-ticket enterprise loans of up to ₹1 lakh through Cluster Level Federations.
- Udyam Gyan Learning Management System (LMS): Developing a technology-enabled platform for continuous learning and capacity building.
- Exposure Visits and Immersion Panchayats: Facilitating enterprise learning, peer exchange and practical exposure to successful enterprise models.
- Livestock Insurance and Financial Solutions: Supporting access to relevant financial solutions to address enterprise-related risks and financing needs.
- Bank and RRB Engagement: Supporting engagement with PSU banks and RRBs through SLBC, DLRC, BLBC and branch/regional/zonal forums to address credit-related bottlenecks and strengthen enterprise financing.
- Digital Credit Facilitation: Supporting the development and refinement of IELA and the wider digital ecosystem for enterprise loan application, processing and tracking.
- Knowledge, Evidence & Learning: Generating evidence, documenting field experience and supporting learning for continuous programme improvement and scale-up.
Key Achievements
Beyond the financing, capacity-building, bank-integration and evidence-generation progress outlined in the chapter, the year’s principal achievement was the operationalisation of digital credit facilitation at scale.
Digital Credit Facilitation: IELA was launched nationwide on 21 February 2026, following pilot testing and field validation. Across the intervention states, 29,729 applications have been initiated, 16,477 submitted to banks, and 2,649 sanctioned.
Way Forward
The next phase will focus on consolidating systems, strengthening digital and banking linkages, documenting outcomes and good practices, and supporting wider adoption of the enterprise-financing approach across the DAY-NRLM/SRLM ecosystem