


Chapter 4 - Section 4.3 - SubSection 4.3.1Expenditure Analysis
Operating costs are a key determinant of the efficiency, competitiveness and financial sustainability of microfinance institutions. Given the sector’s field-intensive operating model, institutions incur high costs in mobilising funds, maintaining a workforce, managing branches and delivering services to borrowers, particularly across rural and underserved markets. The composition of operating expenses therefore provides useful insight into the major cost drivers and the efficiency of institutional operations. In an environment characterised by slower portfolio growth, greater emphasis on responsible lending, and increasing adoption of digital technologies, effective cost management has become more important. At the same time, cost optimisation must be balanced with adequate investment in human resources, technology, risk management, customer service, and borrower protection — all of which ultimately determine how affordably and sustainably the sector can keep extending credit to borrowers who remain outside the reach of mainstream banking. The following analysis examines the distribution of major expense categories and highlights the relative contribution of financial, personnel, administrative, and other expenses to the sector’s overall cost structure.


Figure 4.3.1: Breakdown of expenses under various categories by MLIs2
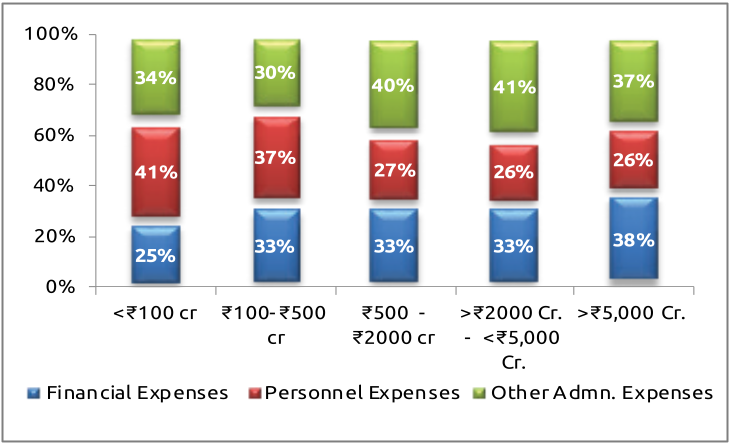
Figure 4.3.2: Break up of expenses by MLIs based on legal form and portfolio size
4.3.1 Expenditure Analysis
Operating costs are a key determinant of the efficiency, competitiveness and financial sustainability of microfinance institutions. Given the sector’s field-intensive operating model, institutions incur high costs in mobilising funds, maintaining a workforce, managing branches and delivering services to borrowers, particularly across rural and underserved markets. The composition of operating expenses therefore provides useful insight into the major cost drivers and the efficiency of institutional operations. In an environment characterised by slower portfolio growth, greater emphasis on responsible lending, and increasing adoption of digital technologies, effective cost management has become more important. At the same time, cost optimisation must be balanced with adequate investment in human resources, technology, risk management, customer service, and borrower protection — all of which ultimately determine how affordably and sustainably the sector can keep extending credit to borrowers who remain outside the reach of mainstream banking. The following analysis examines the distribution of major expense categories and highlights the relative contribution of financial, personnel, administrative, and other expenses to the sector’s overall cost structure.
Figure 4.3.1: Breakdown of expenses under various categories by MLIs2
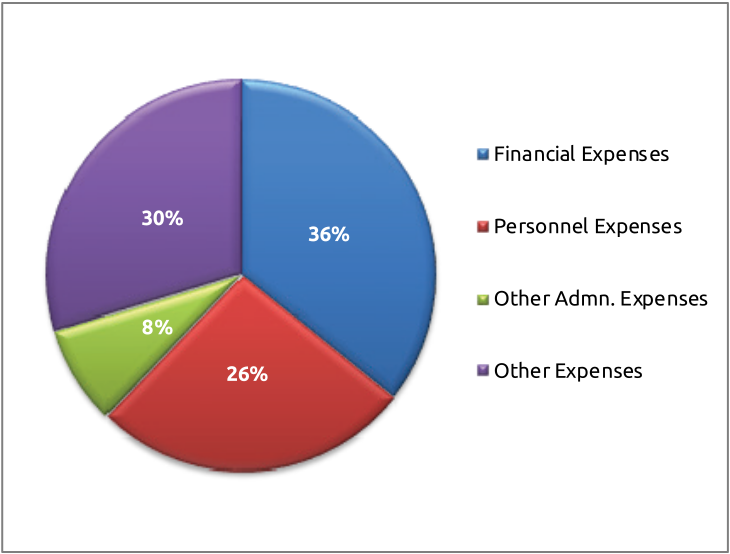
2 Personnel Expenses include salary & wages, including incentive expenses; Other Admin Expenses include expenses incurred on travel, admin, training, and depreciation; Other Expenses include Loan Loss Provision expenses and any other expenses.
The cost structure of microfinance institutions indicates a significant allocation towards financial and operational expenses, reflecting the cost-intensive nature of delivering financial services to underserved and geographically dispersed borrowers. Financial expenses account for the largest share at 36%, followed by other expenses at 30% and personnel expenses at 26%. The remaining 8% is attributable to other admin expenses. Together, financial and other expenses constitute 68%. Here it may be noted that a significant share of the other expenses includes Loan Loss Provision Expenses. Personnel expenses, at over one-fourth of total costs, also underline the continued importance of a field-oriented workforce for customer engagement, credit assessment and portfolio management. The relatively small share of other expenses suggests that the major cost drivers remain the cost of funds, employee-related expenditure and core administrative operations. In the current environment of slower portfolio growth and greater emphasis on efficiency, managing these costs while maintaining service quality and responsible lending practices will be important for the sector’s long-term sustainability.
The higher share of administrative cost is not a very encouraging aspect. The MLIs need to work on this through efficiency in operation, by adopting technology etc and there should be an effort to bring it down so that the ultimate cost will be reduced and the borrowers can be benefitted to that extent.
Figure 4.3.2: Break up of expenses by MLIs based on legal form and portfolio size
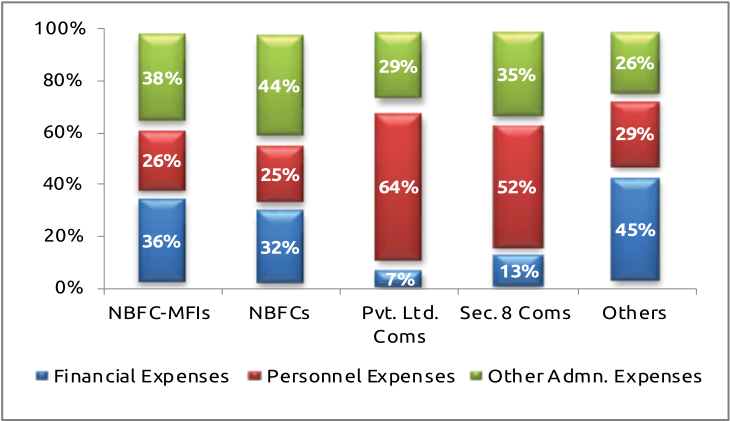
The cost structure varies considerably across legal forms and institutional size, reflecting differences in business models, scale and operating intensity. Among legal forms, NBFC-MFIs have a relatively balanced cost structure, with financial expenses accounting for 36%, personnel expenses 26% and other administrative expenses 38%. NBFCs show a similar pattern, although administrative expenses are higher at 44%. In contrast, Private Limited Companies have a markedly higher share of personnel expenses at 64%, while financial expenses account for only 7% because their financial cost is only for funds needed to meet working capital. Sec. 8 companies also have a relatively high personnel cost share of 52%.
Across institution sizes, the cost structure appears more consistent. Smaller institutions with portfolios below ₹100 crore have the highest personnel expense share at 41%, compared with 25% for financial expenses and 34% for administration. As institutional size increases, the personnel cost component declines, reaching 26% among institutions in the ₹2,000–5,000 crore range, while administrative expenses rise to 41%. Financial expenses remain relatively unchanged at around 33% among institutions above ₹100 crore. Overall, the data suggest that larger institutions benefit from greater scale in personnel deployment, while smaller institutions face relatively higher staff-related costs. The increasing administrative cost share among larger institutions may reflect greater investment in technology, compliance, risk management and institutional infrastructure required to manage larger portfolios.
4.3.1.i Operating Cost3
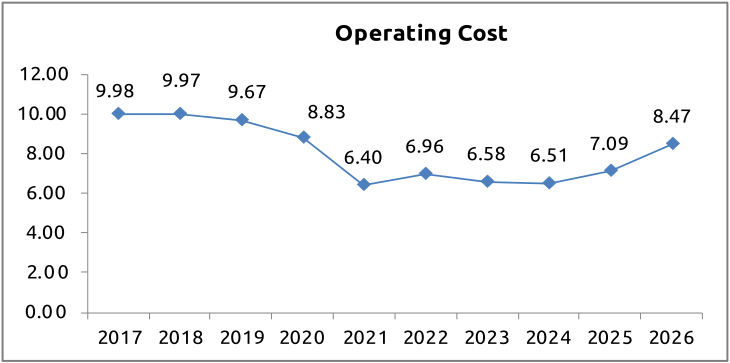
The operating expense ratio is an important measure of the sector’s cost efficiency, indicating operating expenses relative to the scale of business operations. Tracking this ratio over time helps assess changes in institutional efficiency, cost pressures, and microfinance institutions’ ability to manage expenses amid evolving portfolio and operational conditions. The operating cost ratio remained relatively high during 2017–20, declining from 9.98% in 2017 to 8.83% in 2019 before falling sharply to 6.40% in 2021. It remained broadly stable at around 6.5–7.0% during 2022–24, indicating improved cost efficiency. However, the ratio increased to 7.09% in 2025 and further to 8.47% in 2026, signalling renewed operating cost pressures. The 2026 increase may reflect higher staff intensity, investments in compliance and risk management, portfolio-quality management, and slower portfolio growth, which can raise the cost ratio as operating expenses are spread over a slower-growing business base. This rise occurred in a year of unusually benign national consumer-price inflation, reinforcing that it is a sector-specific, structural cost increase rather than one imported from the wider economy. While the ratio remains below the levels observed in 2017–20, the recent upward movement highlights the importance of cost optimisation and productivity improvements for maintaining operational and financial sustainability.
3 Define as (Personnel Cost including incentive + Travel Cost + Admin Cost + Group Dev. Cost/Training Cost + Depreciation + Any Others)/Average Portfolio Outstanding.
Figure 4.3.3: Trends of Operating Cost across MLI Categories4
4 Based on weighted average for all MLIs.
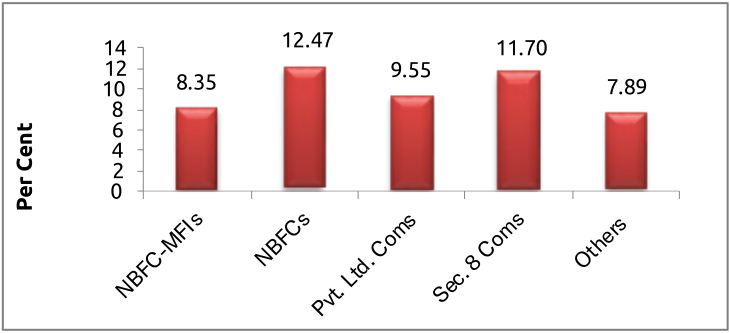
The cost ratio varies considerably across both legal forms and institutional size. By legal form, NBFCs record the highest ratio at 12.47%, followed by Section 8 companies at 11.70% and Private Limited Companies at 9.55%. NBFC-MFIs record a ratio of 8.35%, while Other institutions have the lowest ratio at 7.89%. The relatively higher ratios among NBFCs and Section 8 companies indicate greater operating cost intensity, while the lower ratios among NBFC-MFIs and other institutions suggest comparatively lower operating costs relative to their operating income.
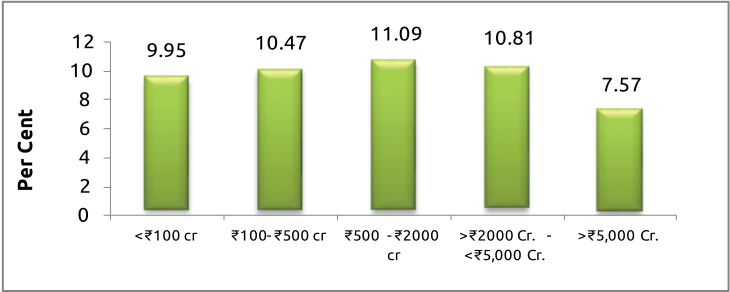
Across portfolio size, the cost ratio generally increases with institutional size up to the ₹500–2,000 crore category, before declining among larger institutions. Institutions with a portfolio below ₹100 crore record a ratio of 9.95%, which rises to 10.47% for those in the ₹100–500 crore range and peaks at 11.09% among institutions with ₹500–2,000 crore portfolios. The ratio then moderates to 10.81% for institutions in the ₹2,000–5,000 crore category and declines substantially to 7.57% among the largest institutions with portfolios above ₹5,000 crore. The substantially lower ratio among the largest institutions points to the benefits of scale, with operating and administrative costs being spread across a larger portfolio. Overall, the distribution highlights the role of scale and cost optimisation in improving operating efficiency, particularly as institutions expand their portfolio.
4.3.1.ii Finance Cost5
Finance cost is a key component of microfinance institutions’ overall cost structure and directly affects their financial sustainability, pricing, and profitability. Given the sector’s dependence on external borrowings and institutional funding, movements in the cost of funds can significantly affect operating margins and lenders’ ability to maintain affordable, sustainable credit. Tracking the finance cost ratio over time indicates changes in funding conditions, borrowing patterns, interest rates, and liability management, and offers a direct read on how faithfully the RBI’s monetary policy cycle is transmitted to the last-mile borrower. The trend also helps assess how institutions have responded to changing market conditions while balancing the need for adequate funding with cost efficiency.
5 Define as the Total expense incurred for acquiring funds /Average Outstanding Borrowings.
Figure 4.3.4: Trends of Finance Cost across MLI Categories6
6 Based on weighted average of all MLIs.
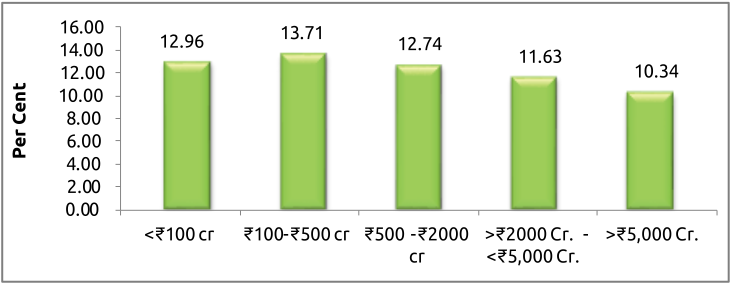
The finance cost shows a clear relationship with institutional scale, with larger institutions generally recording markedly lower funding costs. By portfolio size, finance cost is highest for institutions in the ₹100–500 crore category at 13.71%, followed by those below ₹100 crore at 12.96% and the ₹500–2,000 crore segment at 12.74%. It declines to 11.63% among institutions in the ₹2,000–5,000 crore range and falls to 10.34% for institutions above ₹5,000 crore. This pattern suggests that larger institutions may benefit from better access to diversified, relatively lower-cost funding, stronger credit profiles, and economies of scale in fund mobilisation.
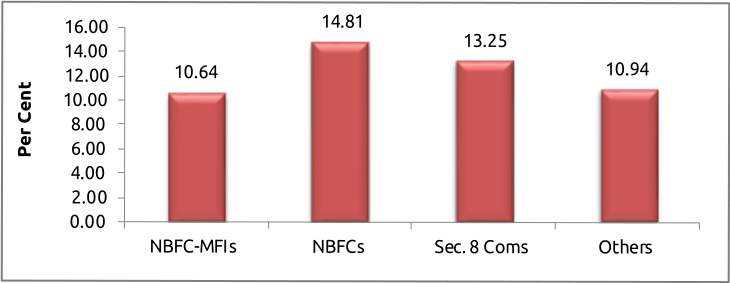
Across legal forms, NBFCs record the highest finance cost at 14.81%, followed by Sec. 8 companies at 13.25% and Other institutions at 10.94%. NBFC-MFIs report a comparatively lower finance cost of 10.64%, despite being the dominant institutional category. The variation may reflect differences in funding sources, access to bank and institutional finance, borrowing terms, creditworthiness and liability structures. In case of NBFC MFIs, the maximum borrowing is done by larger NBFC-MFIs, who generally able to access funds more economically. This could also be reason for an lower average cost of funds for NBFC-MFIs. The share of smaller MFIs which access funds generally at a higher cost, has been less during the year.
Overall, the data reinforce the importance of funding diversification and scale in managing finance costs, particularly for smaller institutions and entities with relatively limited access to low-cost institutional funding.
4.3.1.iii Trends of Operating Cost and Finance Cost
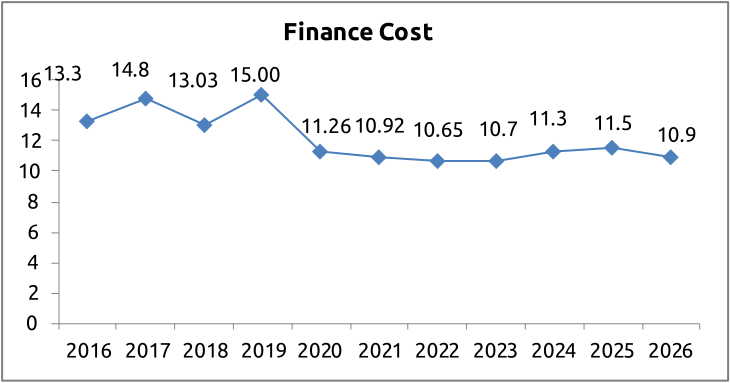
The combined movement of finance cost and operating cost provides a useful perspective on the microfinance sector’s evolving cost structure and sustainability. Finance cost declined substantially from the higher levels observed during 2016–19, when it ranged between 13.0% and 15.0%, to around 10.6–10.9% during 2021–23. Finance cost then increased to 11.5% in 2025 before moderating marginally to 10.9% in 2026 — a moderation that tracks closely with the RBI’s own rate actions, which cut the repo rate by 25 basis points in December 2025 and held it at 5.25% in February 2026 on the back of a softer inflation outlook7. That the sector’s own cost of funds eased only marginally despite this policy support suggests transmission remains incomplete, and that funding pressures continue to matter more for some institutions than the headline number implies.
Operating cost followed a different trajectory. It declined sharply from around 10% in 2017–18 to 6.4% in 2021, remaining broadly contained through 2024. However, it increased to 7.09% in 2025 and further to 8.47% in 2026 — even as the broader economy grew by an estimated 7.4% and inflation stayed low, underlining that this is a cost story written inside the sector rather than one imposed from outside it. This recent rise is particularly significant when viewed alongside the workforce trends discussed earlier. Staff strength declined in 2026, but the client-to-staff ratio also fell sharply to 210, suggesting that institutions are deploying greater staff intensity per client. Higher expenditure on collection of dues, compliance, risk management, borrower engagement and portfolio monitoring may also be contributing to the increase in operating costs.
Taken together, finance and operating costs amounted to approximately 19.4% in 2026, compared with around 18.6% in 2025 and 17.8% in 2024. Thus, despite lower finance costs, rising operating costs have pushed the overall cost burden upward — and they have done so even as the RBI’s own easing cycle was working in the sector’s favour on the funding side, which means the net increase in the all-in cost ratio is, if anything, an understatement of how much operating costs alone have risen. This has important implications for the sector: with portfolio growth moderating and credit-quality pressures persisting, institutions may have less scope to absorb rising costs without affecting margins. At the same time, the higher operating intensity may support better underwriting, collections and borrower protection.
The key challenge for the sector is therefore not simply cost reduction, but achieving productivity-led efficiency, leveraging technology and scale to contain costs while preserving adequate investment in frontline staff, risk management and responsible lending. This is also the space in which the RBI’s principles-based pricing framework for microfinance loans8 operates: institutions set interest rates through a board-approved policy rather than a prescribed cap, which means cost discipline, and not regulation alone, is what will ultimately determine how much of the current cost pressure gets passed on to borrowers. The substantially lower cost ratios among the largest institutions further indicate the potential benefits of scale and funding diversification, while smaller and mid-sized institutions may face greater pressure to improve operational efficiency and access more competitive funding.