


Chapter 4 - Section 4.5 - SubSection 4.5.2.iiiDebt Funding
Since most of the MLIs are not allowed to mobilise deposits, debt funding becomes very important for microfinance operations. The funding structure of microfinance institutions is a key determinant of their liquidity, cost of funds and capacity to sustain lending operations. Given the sector’s reliance on external funding to support loan portfolios, the composition of liabilities provides insight into the extent of funding diversification and institutions’ access to different sources of finance. Examining the mix of borrowings, debt instruments, bonds, ECBs and other sources helps assess the sector’s funding resilience and ability to manage changing market conditions and funding costs.


Sources of funding based on types of instruments
Sources of funding based on Institution types
Outstanding Borrowings (₹ in Cr.) – Yearly Trend
Outstanding Borrowings (₹ in Cr.) – MLI-Category-wise Break-up of 2026 (Legal Form)
Outstanding Borrowings (₹ in Cr.) – MLI-Category-wise Break-up of 2026 (Portfolio Size)
Fund Received during the year and MLI-Category-wise Break-up of 2026
4.5.2.iii Debt Funding
Since most of the MLIs are not allowed to mobilise deposits, debt funding becomes very important for microfinance operations. The funding structure of microfinance institutions is a key determinant of their liquidity, cost of funds and capacity to sustain lending operations. Given the sector’s reliance on external funding to support loan portfolios, the composition of liabilities provides insight into the extent of funding diversification and institutions’ access to different sources of finance. Examining the mix of borrowings, debt instruments, bonds, ECBs and other sources helps assess the sector’s funding resilience and ability to manage changing market conditions and funding costs.
Figure 4.5.5: Sources of funding based on types of instruments
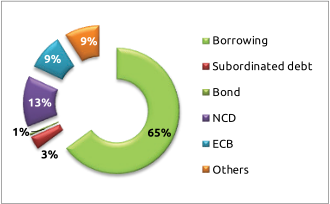
The funding structure indicates that borrowing from banks, DFIs and other financial institutions, remains the dominant source of external funding, accounting for 65% of total funds. This is followed by NCDs at 13%, while ECBs and other sources each contribute 9%. Subordinated debt accounts for 4%. This heavy reliance on borrowing highlights the sector’s continued dependence on bank and institutional finance to support lending operations. At the same time, the presence of ECBs, NCDs and other market-based instruments indicates some diversification of funding sources. A broader funding mix can help institutions manage liquidity and funding costs, although access to market-linked sources may vary significantly by institutional size and credit profile. Overall, the funding structure underscores the importance of diversifying liabilities and maintaining stable, cost-efficient sources of finance, particularly for smaller institutions that may have more limited access to capital markets.
The funding distribution by source indicates that the private sector is the largest provider of funds to microfinance institutions, accounting for 37% of total funding. This is followed by the public sector and other categories, contributing 15%, each. While NCDs account for 14%. NBFCs contribute a further 6%, with NABARD at 3%, MUDRA at 1%, and other financial institutions at 7%. SIDBI sources account for the remaining 2%.
Figure 4.5.6: Sources of funding based on Institution types
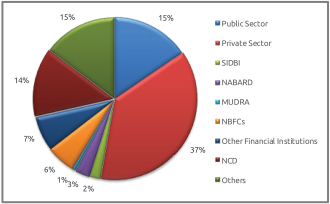
The composition reflects a diversified funding ecosystem, with both banks and financial institutions playing an important role alongside market-based debt instruments. The substantial private-sector contribution highlights the importance of commercial lenders in supporting microfinance operations. In contrast, the combined contribution of public-sector institutions and development-oriented lenders such as SIDBI and NABARD provides an important channel for institutional and potentially longer-term funding. The 14% share of NCDs also indicates growing relevance of market-based funding. Overall, the distribution suggests that the sector has access to multiple funding channels, which can help institutions manage liquidity and reduce dependence on any single source. At the same time, the dependence on borrowing still very high and the sector need to move into other market instruments to have better access to funding without relying on borrowing.
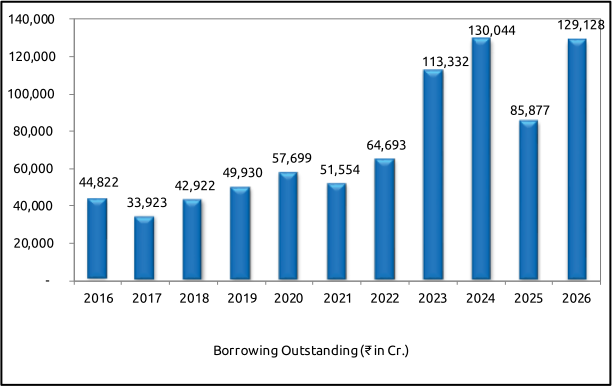
Borrowing outstanding has expanded substantially over the past decade, rising from ₹44,822 crore in 2016 to ₹1,29,128 crore in 2026. After a decline to ₹33,923 crore in 2017, borrowings increased steadily through 2020, with a temporary moderation in 2021. The pace of growth accelerated significantly thereafter, reaching ₹1,13,332 crore in 2023 and peaking at ₹1,30,044 crore in 2024. Borrowings fell sharply to ₹85,877 crore in 2025, then recovered strongly in 2026 to ₹1,29,128 crore, a 50.4% year-on-year increase.
The recovery of microlending towards the end of FY 2026 reflects on the renewed access to external funding following the contraction observed in 2025. The introduction of Credit Guarantee Scheme for MFI 2.0 in March 2026, may not have been made use of in FY 2026. But provide a positive sentiment to the funders.
The near return to the 2024 peak also suggests institutions have rebuilt their borrowing capacity to support lending operations and liquidity requirements. This trend aligns with the broader recovery in the sector’s outstanding portfolio and indicates continued reliance on external borrowings as the principal source of funding. At the same time, significant year-to-year fluctuations highlight the importance of maintaining diversified, stable funding channels to manage liquidity and funding-cost risks.
Figure 4.5.7: Outstanding Borrowings (₹ in Cr.) – Yearly Trend and MLI-Category-wise Break-up of 2026
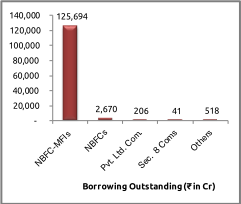
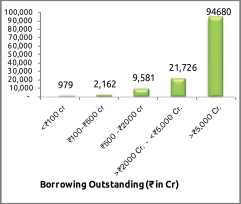
The distribution of borrowing outstanding in 2026 shows a strong concentration among NBFC-MFIs and the largest institutions. By legal form, NBFC-MFIs account for ₹1,25,694 crore, representing the overwhelming majority of total borrowings, while NBFCs account for ₹2,670 crore and other legal forms contribute relatively small amounts. By portfolio size, institutions with portfolios above ₹5,000 crore hold ₹94,680 crore of borrowings, followed by the ₹2,000–5,000 crore category at ₹21,726 crore and the ₹500–2,000 crore category at ₹9,581 crore. Together, institutions ‘above ₹2,000 crore’ account for most outstanding borrowings.
This concentration reflects larger MLIs’ scale of operations and greater access to institutional funding. Larger institutions are likely to have stronger credit profiles, established lender relationships and greater ability to access diverse funding instruments. In contrast, smaller institutions have significantly lower outstanding borrowings, which may reflect smaller portfolios and comparatively limited access to large-scale institutional finance. The distribution also reinforces the sector’s dependence on NBFC-MFIs as the principal borrowers and highlights the need to diversify funding and improve access to competitive finance for smaller and mid-sized institutions.
Borrowing Received
The microfinance sector received ₹1,07,081 crore by way of borrowings during FY 2026, with NBFC-MFIs accounting for ₹1,05,208 crore, or nearly 98% of total borrowing received. NBFCs received ₹1,553 crore, while other legal forms accounted for relatively small amounts. The concentration is similarly pronounced by institutional size, with institutions having portfolios above ₹5,000 crore receiving ₹86,532 crore, followed by the ₹2,000–5,000 crore category at ₹12,789 crore and the ₹500–2,000 crore category at ₹6,391 crore.
Figure 4.5.8: Fund Received during the year and MLI-Category-wise Break-up of 2026
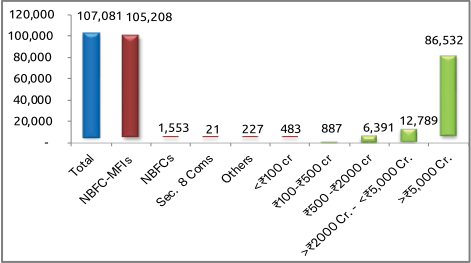
The distribution indicates that larger institutions continue to attract most fresh debt funding, reflecting that the small and medium ones have still to gain the confidence of the funders. The CGSMFI 2.0 is likely to change this sentiment. The strong concentration of borrowing among larger NBFC-MFIs also reflects the sector’s structure, where these institutions account for most lending activity. Overall, the data indicate strong mobilisation of debt funding in FY 2026, while highlighting the continuing need to broaden access to stable and competitively priced debt for smaller and mid-sized institutions.
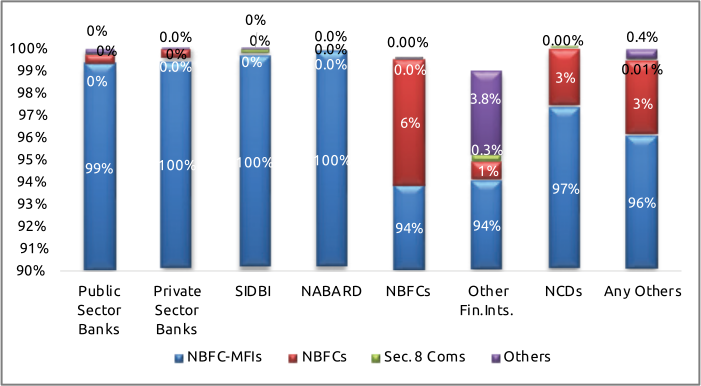
Table 4.5.1 and Figure 4.5.9 below illustrate the debt received by MLIs from various source types.
Table 4.5.1: Source wise fund received (in ₹ Cr.) by different entities during the year
| Public Sector Banks | Private Sector Banks | SIDBI | NABARD | NBFCs | Other Fin. Ints. | NCDs | Any Others | |
|---|---|---|---|---|---|---|---|---|
| NBFC-MFIs | 15,893 | 51,548 | 1,214 | 1,558 | 7,075 | 2,643 | 7,366 | 17,910 |
| NBFCs | 70 | 220 | - | - | 421 | 23 | 194 | 626 |
| Pvt. Ltd. Com. | 2 | 1 | - | - | 37 | 27 | - | 5 |
| Sec. 8 Coms | 8 | - | 2 | - | 1 | 8 | 0.20 | 1 |
| Others | 37 | 4 | 0.25 | - | 0.30 | 107 | - | 79 |
| Total | 16,010 | 51,773 | 1,217 | 1,558 | 7,535 | 2,808 | 7,560 | 18,621 |
Figure 4.5.9 : Source-wise Share of Loans lent among Different Legal Forms of MLIs during 2025-26
Major lenders to MLIs during 2025-26
The tables below list the major lenders (based on the information received for the top 10 lenders for each institution) that provide debt funds to MLIs.
Table 4.5.2 (a): List of banks that lent to MLIs as of March 2026 (Based on the Top 10 lenders out of the total)
| Sl. No. | Name of Lenders | No. of MLIs |
|---|---|---|
| 1 | Assam Cooperative Apex Bank (ACAB) | 1 |
| 2 | Assam Gramin Vikash Bank | 1 |
| 3 | AU Small Finance Bank | 3 |
| 4 | Axis Bank Ltd. | 10 |
| 5 | Bandhan Bank Ltd. | 8 |
| 6 | Bank of Baroda | 10 |
| 7 | Bank of Maharashtra | 6 |
| 8 | Canara Bank | 2 |
| 9 | City Union Bank | 1 |
| 10 | CSB Bank Ltd. | 1 |
| 11 | DBS Bank India Ltd. | 2 |
| 12 | DCB Bank Ltd. | 4 |
| 13 | District Central Co-operative Bank | 1 |
| 14 | Equitas Small Finance Bank | 1 |
| 15 | ESAF Small Finance Bank | 1 |
| 16 | Federal Bank Ltd. | 7 |
| 17 | HDFC Bank Ltd. | 3 |
| 18 | HSBC Bank Ltd. | 7 |
| 19 | ICICI Bank Ltd. | 8 |
| 20 | IDBI Bank Ltd. | 4 |
| 21 | IDFC First Bank Ltd. | 18 |
| 22 | Indian Bank | 1 |
| 23 | Indian Overseas Bank | 7 |
| 24 | IndusInd Bank Ltd. | 2 |
| 25 | Jana Small Finance Bank | 6 |
| 26 | Karur Vysya Bank | 3 |
| 27 | Kotak Mahindra Bank Ltd. | 2 |
| 28 | NABARD | 1 |
| 29 | NE Small Finance Bank | 1 |
| 30 | Pudhuvai Bharathiyar Grama Bank | 1 |
| 31 | Punjab & Sind Bank | 1 |
| 32 | RBL Bank Ltd. | 3 |
| 33 | REPCO Bank | 1 |
| 34 | SBM Bank Ltd. | 2 |
| 35 | Shivalik Small Finance Bank | 1 |
| 36 | SIDBI | 9 |
| 37 | Standard Chartered Bank | 4 |
| 38 | State Bank of India | 21 |
| 39 | State Bank of Mauritius | 2 |
| 40 | Suryoday Small Finance Bank | 1 |
| 41 | Tamil Nadu Grameen Bank | 1 |
| 42 | The Assam Co-operative Apex Bank Ltd. | 1 |
| 43 | UCO Bank Ltd | 4 |
| 44 | Union Bank of India | 9 |
| 45 | West Bengal Gramin Bank | 2 |
| 46 | Yes Bank Ltd. | 6 |
Table 4.5.2 (b): List of other lenders who lent to MLIs as of March 2026 (Based on the Top 10 lenders out of the total)
| Sl. No. | Name of Lenders | No. of MLIs |
|---|---|---|
| 1 | AK Capital Services Ltd. | 1 |
| 2 | Ambium Finserve Pvt. Ltd. | 1 |
| 3 | Annapurna Finance Pvt. Ltd. | 4 |
| 4 | Archbridge Capital Pvt. Ltd. | 1 |
| 5 | Arohan Financial Services Ltd. | 20 |
| 6 | Assam Finance Corporation (AFC) | 4 |
| 7 | Asvanta Financial Consultants Pvt. Ltd. | 2 |
| 8 | Aurukshaya Consultants Pvt. Ltd. | 1 |
| 9 | Avanti Finance Pvt. Ltd. | 2 |
| 10 | Baid Finserv Ltd. | 2 |
| 11 | Bajaj Finance Ltd. | 1 |
| 12 | Barclays Bank PLC | 1 |
| 13 | Blacksoil Capital Pvt. Ltd. | 3 |
| 14 | Blue Orchard Microfinance Fund | 2 |
| 15 | Carron Capital LLP | 1 |
| 16 | Caspian Investments Pvt. Ltd. | 1 |
| 17 | Concard Financiers Pvt. Ltd. | 1 |
| 18 | Creation Investments Capital Management | 1 |
| 19 | Electronica Finance Ltd. | 1 |
| 20 | Finstars Capital Ltd. | 1 |
| 21 | Floras | 1 |
| 22 | FMO | 1 |
| 23 | Fuherer Capital Pvt. Ltd. | 1 |
| 24 | FWWB | 18 |
| 25 | Global Gender Smart Fund (Incofin) | 1 |
| 26 | Godavari Urban Multistate Credit Co-operative Society | 1 |
| 27 | Gosree Finance | 1 |
| 28 | Grip Invest Technologies Pvt. Ltd. | 3 |
| 29 | Hero FinCorp Ltd. | 1 |
| 30 | Hindon Mercantile Ltd. | 1 |
| 31 | Hinduja Leyland Finance | 1 |
| 32 | IBL Finance Ltd. | 3 |
| 33 | IFMR Fimpact | 1 |
| 34 | IIX Global | 1 |
| 35 | InCred Financial Services Ltd. | 2 |
| 36 | Infina Finance Pvt. Ltd.(IFPL) | 1 |
| 37 | IRIS | 1 |
| 38 | Jackson Commercial Pvt. Ltd. | 1 |
| 39 | Janasha Finance Pvt. Ltd. | 1 |
| 40 | Jeevan Utthan Financial Services Pvt. Ltd. | 2 |
| 41 | Kaleidofin Capital Pvt. Ltd. | 4 |
| 42 | Kamdhenu Financial Services Pvt. Ltd. | 1 |
| 43 | Karnataka State Financial Corporation | 1 |
| 44 | Kashi Vishwanatha Vidya Samasthe | 1 |
| 45 | Kiara Microcredit | 1 |
| 46 | Kissandhan Agri Financial Services Pvt. Ltd. | 2 |
| 47 | Kiyansh Finance Pvt. Ltd. | 2 |
| 48 | Kula International | 1 |
| 49 | Lord Fincap Ltd. | 1 |
| 50 | Maanaveeya Development & Finance Pvt. Ltd. | 6 |
| 51 | Manappuram Finance Ltd | 1 |
| 52 | MAS Financial Services Ltd. | 13 |
| 53 | Microfinance Solidaire | 1 |
| 54 | MILAAP | 3 |
| 55 | Money Wise Financial Services Pvt. Ltd. | 2 |
| 56 | Moringway | 1 |
| 57 | Mufin Green Finance Ltd. | 1 |
| 58 | Muthoot Microfin Ltd. | 1 |
| 59 | NABFINS Ltd. | 3 |
| 60 | NABKISAN Finance Ltd. | 2 |
| 61 | Naman Finlease Ltd. | 1 |
| 62 | National Cooperative Development Corporation (NCDC) | 2 |
| 63 | NEDFi | 7 |
| 64 | Neo Markets Services Pvt. Ltd. | 1 |
| 65 | Nipha Finance Pvt. Ltd. | 1 |
| 66 | NKC Finance Pvt. Ltd. | 2 |
| 67 | Northern Arc Capital Ltd. | 13 |
| 68 | Nova Vyapar Pvt. Ltd. | 1 |
| 69 | OXY Venture | 1 |
| 70 | Oxyzo Financial Services Ltd. | 3 |
| 71 | PAFT Finance Ltd. | 1 |
| 72 | Pagasa Consultancy Pvt.Ltd. | 1 |
| 73 | Phillip Capital | 1 |
| 74 | Pinoy Consultancy Pvt. Ltd. | 1 |
| 75 | Piramal Finance Ltd. | 4 |
| 76 | Rajputana Investment and Finance Ltd. | 1 |
| 77 | RAR Fincare Ltd | 7 |
| 78 | Real Touch Finance Ltd. | 1 |
| 79 | ResponsAbility | 1 |
| 80 | Rockland Finstock Ltd. | 1 |
| 81 | Sabrimala Fintech Pvt. Ltd. | 2 |
| 82 | Sahabhagi Services Pvt. Ltd. | 1 |
| 83 | Saidhan Mercantile Pvt. Ltd. | 1 |
| 84 | Samunnati Services Pvt.Ltd. | 1 |
| 85 | SAS Finserv Pvt. Ltd. | 1 |
| 86 | Satin Creditcare Network Ltd. | 1 |
| 87 | SAVE Solutions Pvt. Ltd. | 1 |
| 88 | Share Bazar Financial Pvt. Ltd. | 1 |
| 89 | Shine Star Build Cap Pvt. Ltd. | 2 |
| 90 | Shriram Finance Ltd. | 11 |
| 91 | SK Finance Ltd. | 1 |
| 92 | SV Creditline Ltd. | 1 |
| 93 | Tamilnadu Industrial Investment Corporation (TIIC) Ltd. | 1 |
| 94 | Tata Capital Ltd. | 3 |
| 95 | The Kangra Central Co-op Bank Ltd. | 1 |
| 96 | Tipsons Consultancy Services Pvt. Ltd. | 1 |
| 97 | Triodos Investment Management BV | 1 |
| 98 | Tuvis Services | 1 |
| 99 | UC Inclusive Credit Pvt.Ltd. | 9 |
| 100 | Usha Financial Services Pvt. Ltd | 8 |
| 101 | UTI Responsibility | 1 |
| 102 | Viridian Capital and Financial Services Pvt. Ltd. | 2 |
| 103 | Vivriti Capital Pvt. Ltd. | 10 |
| 104 | Western Capital Advisors Pvt. Ltd. | 1 |
| 105 | Wint Wealth | 1 |
| 106 | WLB Asset Vii PTE Ltd . | 1 |