Glossary
ABCO
ABCO is an acronym for Active Borrower per
Credit Officer. It is a key operational metric
in microfinance that measures the client-to-
credit officer ratio, indicating the average
number of active borrowers managed by each
credit officer. It is also commonly referred to
as the Case Load. This will also indicate the
efficiency of operation, which can impact the
operational expenses
Active Borrowers
The individuals whose loan accounts are
current have an outstanding loan balance with
the MFI, and are under repayment obligation.
Individuals who have multiple loans with an
MFI should be counted as a single borrower.
Assets Under Management (AUM)
Assets Under Management (AUM) refers to
the total value of client loan portfolios that an
institution actively manages, including both on-
book and off-balance sheet (off-BS) portfolios.
This includes all outstanding principal from
current, delinquent, and renegotiated loans,
but excludes loans that have been written off,
on the own book, as well as those securitized
or direct assignment assets resting on the
securitization partners. AUM reflects the
overall scale of financial assets the institution
is responsible for, regardless of ownership.
Average Loan Size
Average Loan size represents the client-per-
capita loan amount. It is calculated as the Loan
portfolio divided by the number of clients of
an MFI. It is a key indicator used to assess the
scale and depth of credit outreach.
Average Ticket Size (ATS)
Average Ticket Size (ATS) refers to the average
loan amount disbursed per loan during a
specific period of time. This metric is typically
calculated for a defined time period such as
monthly, quarterly, or annually, depending on
the reporting or analysis needs. It is calculated
as the Total Loan Amount Disbursed divided
by the Total Number of Loans Disbursed.
Borrowing Cost
The cost of borrowing refers to the total charge
incurred for taking a debt obligation, which
includes interest payments as well as any
additional financial fees (such as processing
fees, service charges, insurance premiums,
or administrative costs). A percentage of such
cost over the total amount borrowed indicates
the rate of such cost.
Capital Adequacy Ratio
Capital Adequacy is a key financial indicator
used to measure the solvency and risk-bearing
capacity of Microfinance Institutions (MFIs).
It reflects the institution’s ability to absorb
potential losses and protect depositors and
creditors. It is the proportion of the equity
capital and free reserves or own funds held by
an MFI against its total risk-weighted assets.
A higher Capital Adequacy Ratio indicates
stronger financial health and a greater ability
to withstand credit or operational shocks. A
minimum requirement of an NBFC-MFI is 15%.
Capital to Total Assets
The Capital to Total Assets ratio is a measure of
an institution’s financial strength and stability.
It indicates the proportion of an institution’s own capital (or net worth) relative to its total
assets.
Co-lending
Co-lending is a financial arrangement in which
two or more regulated entities join hands
to extend a loan, by taking a fixed share by
each entity. It will reflect on the books of all
the partnering institutions. Typically, a bank
and a non-bank financial institution (NBFC
or NBFC-MFI) or HFC can join together to
extend credit to a borrower and a prefixed
ratio at a weighted average interest rate. The
partnership combines the strengths of both
entities.
Debt-Equity Ratio
The Debt-Equity Ratio is a key financial metric
that indicates the proportion of total debt to
total equity held by an institution at a given
point in time. It reflects the degree to which
an organization is financing its operations
through borrowed funds versus own funds or
free capital. It also indicates the leverage of
capital of an entity
Debt Funding
Debt Funding refers to the portion of a financial
institution’s loan portfolio that is financed
through external borrowings, rather than from
internal accruals or equity capital. It reflects
the extent to which an institution relies on
borrowed funds, such as loans from banks,
financial institutions, or capital markets, to
support its lending activities.
External Cost
External Cost refers to the finance cost
incurred by Microfinance Institutions (MFIs)
on the borrowed funds from external sources,
primarily banks and financial institutions. This
cost is largely determined by the prevailing lending rates of banks, and as such, it is
beyond the direct control of MFIs.
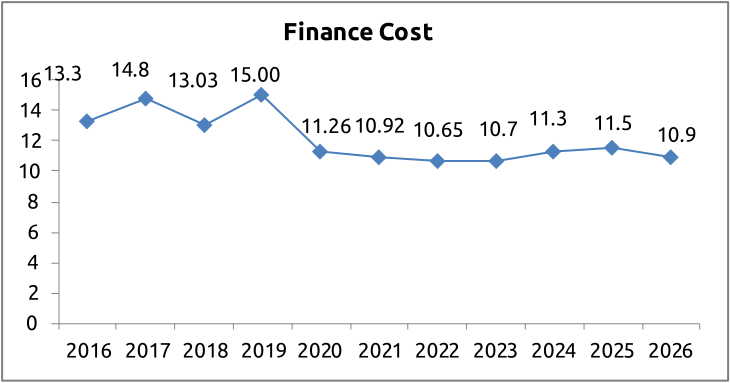
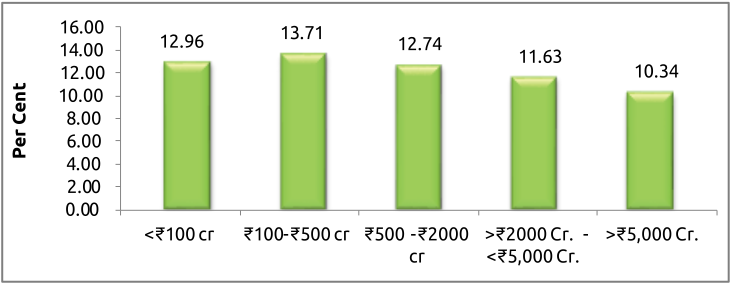
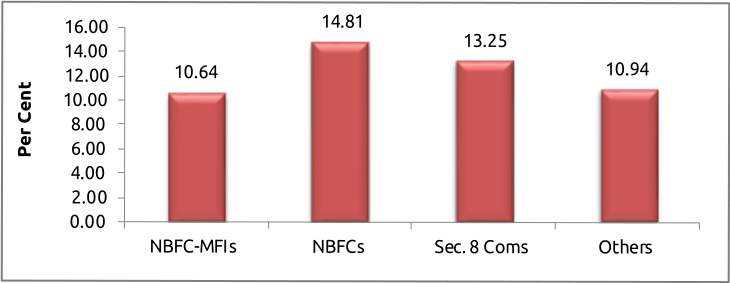
Finance Cost
Finance Cost refers to the actual interest
and other financial expenses incurred by a
Microfinance Institution (MFI) on the average
borrowed funds that remain outstanding
during a given period. This metric is crucial
for evaluating the cost-efficiency and funding
strategy of MFIs, and plays a key role in
determining their lending rates and financial
sustainability.
Financial Inclusion
Financial Inclusion refers to the delivery
of affordable, accessible, and appropriate
financial services to disadvantaged and
low-income segments of society who are
traditionally excluded from the formal financial
system. These services include savings, credit,
insurance, remittances, pensions, banking
services, etc.
Joint Liability Groups
Groups of 4 to 8 borrowers come together
to borrow from a financial institution under
a joint liability concept, as per which there is
an inter se agreement between the members
whereby each borrower is liable to repay the
loan of each member of the group.
Margin
Margin refers to the difference between
the total yield on the loan portfolio and the
finance cost incurred to fund that portfolio.
It represents the net earnings a Microfinance
Institution (MFI) makes from its lending
activities before operating expenses and
provisions.
Managed Loan Portfolio
Managed Loan Portfolio refers to the loan
assets originally originated by Microfinance
Institutions (MFIs) but subsequently sold
or assigned to a third party, such as a bank,
to improve liquidity. Despite the sale, MFIs
continue to manage these loans, including
activities like collection of repayments and
servicing the accounts on behalf of the
purchasing institution. This arrangement
helps MFIs free up capital while maintaining
their relationship with borrowers and ensuring
ongoing portfolio management.
Non-Performing Assets (NPA)
A Non-Performing Asset (NPA) is a debt
obligation where the borrower has failed
to honour repayment commitments, either
interest, principal, or both, to the designated
lender for a specified period, typically 90 days
or more. As a result, the NPA ceases to generate
income for the lender in the form of interest or
principal repayments. NPAs represent credit
risk and affect the financial health and asset
quality of lending institutions.
On-book Portfolio (Net Loan Portfolio)
On-book Portfolio (Net Loan Portfolio) refers to
the total outstanding principal of all active client
loans recorded on the institution’s balance
sheet. This includes current, delinquent, and
renegotiated loans, but excludes loans that
have been written off. Interest receivable
is not included, except for Microfinance
Institutions (MFIs) that report under Ind-AS,
where such interest is recognized as part of
the outstanding amount.
Operating Self Sufficiency (OSS)
Operating Self Sufficiency (OSS) measures
the extent to which a Microfinance Institution’s (MFI’s) income from operations
and investments is sufficient to cover its
operating expenses, like operating costs, loan
loss provisions, and finance costs (cost of
borrowed funds) incurred for conducting the
operations. An OSS ratio of 100% or above
indicates that the MFI is generating enough
income to sustain its operations without
requiring subsidies or external support,
reflecting financial viability and sustainability.
Outstanding Borrowings
Outstanding Borrowings refer to the total
amount of funds that an entity has borrowed
and has not yet repaid as of a specific reporting
date. This includes all short-term and long-
term debt obligations, such as loans, credit
lines, bonds, and other forms of financing, net
of any repayments made.
Portfolio Quality
Portfolio Quality refers to the level of credit
risk present in a loan portfolio, indicating the
likelihood of default by borrowers. A high-
quality portfolio contains a lower amount of
risk, characterized by timely repayments and
minimal defaults. Maintaining good portfolio
quality is crucial for the financial health and
sustainability of lending institutions.
Portfolio at Risk (PAR)
Portfolio at Risk (PAR) indicates the
proportion of outstanding amounts of all loan
accounts having past due/arrears to the total
outstanding loan. In general, PAR 30 refers
to the percentage of the loan portfolio that
remains unpaid 30 days or more beyond the
due date, which would be used as a measure
to assess the portfolio quality. Loans with
dues overdue by 90 days or more (PAR 90) are
generally classified as Non-Performing Assets
(NPAs).
Qualifying Assets
Qualifying Assets are loan portfolios created
by MFIs adhering to certain conditions as
prescribed by RBI, to make the MFIs eligible
to be called as MFIs and to raise loans from
banks under the Priority Sector Advances
Scheme (as per recent RBI norms). For an MFI,
60% of the total ass ets need to be under this
category
Return on Assets (RoA)
Return on Assets (RoA) is the universally
accepted profitability measure, which, in
essence, is the percentage net income earned
out of total average assets deployed by MFIs
during a given period, typically one financial
year. It is a widely used profitability metric that
measures how efficiently an institution utilizes
its total assets to generate net income.
Return on Equity (RoE)
Return on Equity (RoE) is a key profitability
indicator that measures the net income earned
by a Microfinance Institution (MFI) relative
to its average equity during a given period,
typically one financial year. RoE reflects how
efficiently an MFI is using its own capital
(equity) to generate profits.
Self Help Groups (SHGs)
SHGs refer to groups of 10-20 persons coming
together to form an informal community-based
institution to meet their common financial and
social needs. Most of the SHGs are formed by women from a homogeneous background.
SHGs collect regular savings from members
and use them for internal lending, before
accessing higher amounts from banks.
SHG Bank Linkage Programme (SBLP)
SHGs are linked to mainstream banks for
keeping their surplus savings and also to
obtain loans. The loan is often given as a
multiplier of the total internal savings accrued
in a group. It is considered to be an effective
strategy to ensure financial inclusion for the
unbanked poor people.
Surplus
Surplus refers to the excess of income over
expenses. It is calculated as the difference
between the yield (i.e., income earned
from the loan portfolio) and the total cost
(including finance cost, operating expenses,
and provisions). It can also be referred to as
net margin.
Yield on Portfolio
Yield represents total income from microcredit
operation - interest income, processing fee/
service charge – earned out of the average
loan portfolio outstanding for a specific period.
It does not include investment income. It is a
good proxy/surrogate for loan interest rates.
It serves as a useful proxy for the effective
loan interest rate charged to clients and is
often used to assess the pricing structure and
earning capacity of the loan portfolio.